 STRATAGEM LABS
Executive summary
An early AI proposal can offer a precise return before there is enough evidence to support it. The article separates exploration, validation and scaling: fund a bounded learning exercise first, test adoption and unit economics next, and use conventional investment valuation when measured performance supports credible cash-flow forecasts.
A number with nothing under it
A friend of mine in India has been dreaming about building a house, not in the city but away from the chaos on a hillock about 90-100 minutes from the city. His idea - not buying one, building one, from a piece of land he fell for on a drive through the hills. We were having coffee the other week and I asked him, mostly out of curiosity, what the whole thing would cost. All in. And he told me. A number. A confident one, down to the last few thousand, the kind of number you could write on a loan application without blinking.
Here is the thing. There is no design yet. No architect, no soil test, no idea whether that pretty slope needs retaining walls that cost more than the house. He has a feeling, a Pinterest board, and a very precise number hanging off the end of both. (I said none of this out loud, of course. You do not do that to a friend who is happy.)
But I have been thinking about that number ever since, because it is the same number, the confident one with nothing under it, that turns up in AI business case after AI business case, whether in informal discussions I am part of, formal conversations assisting clients with their AI initiatives, or the conferences I have been attending lately. And while I could get away with politely nodding at my friend's dream-house number, the finance leaders staring at one cannot.
The wrong financial tool
The AI version arrives dressed as a business case. A team wants a few hundred thousand dollars for a system that, if it works, could change a core process. You ask the question finance has always asked, what is the return, and back comes a spreadsheet with a discount rate and a five-year horizon and an internal rate of return that clears your hurdle. It looks like rigour. It is my friend's house. Those cash flows are not forecasts, they are a confident answer to a question nobody in the room can answer yet, because none of them knows whether the thing even works.
The reflex, when you sense the number is soft, is to ask for more rigour. Tighter model, firmer ROI, a better forecast before a single dollar moves. I understand the instinct, and it happens to be the one that quietly does the most damage, because it reaches for a tool built for a different job. A net present value is a lovely instrument when you can estimate the cash flows, when you are buying a machine whose output you can project, or opening a store in a market you already understand. It runs on predictability. An early AI project has none to give it. Force the predictable-cash-flow tool onto an unpredictable thing and it does not merely hand you a wrong answer, it hands you a confident wrong answer, which is worse, because now the guess is wearing a suit and the whole room trusts it.
Name the stage
So the useful move is not to argue harder about the number. It is to ask one question before the number even comes up: what stage is this?
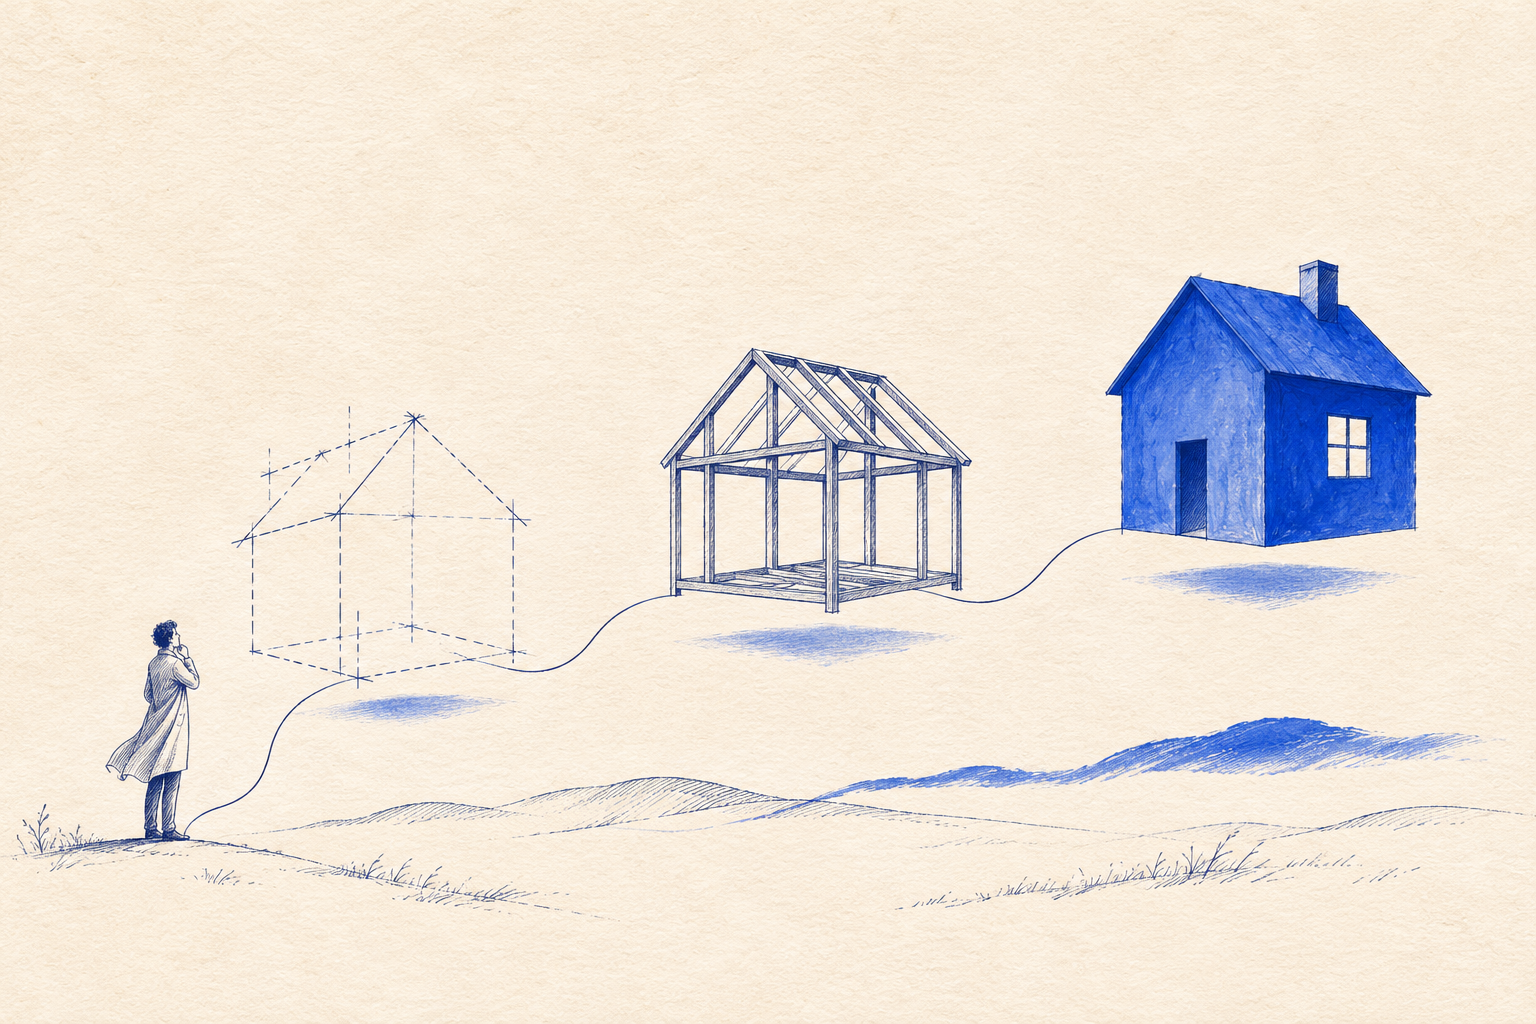
That sounds almost too plain to be a finance tool. It is close to the whole discipline. An AI investment is not one thing you value once and for all. It is three things in sequence, and the uncertainty drains out of it as it matures, so the honest way to value it keeps changing underneath you while you are still staring at the first spreadsheet. Name the stage, and the right tool falls out on its own. Argue the number without naming the stage, and you will pick up the wrong tool almost every time.
Exploration, validation and scaling
When you genuinely cannot yet say whether the thing works, you are in exploration, and here NPV is not just unreliable, it is impossible. There are no cash flows to discount, only a hypothesis to test. The question that actually fits is a smaller, braver one: what is the most we would pay to learn whether this works, and what result would tell us either way? You are not buying the product at this point. You are buying the answer, and the right to build the product later if the answer comes back yes. So you keep the money deliberately small, you fix the date by which you will decide, and you write down, before you start, the result that lets it go forward and the result that kills it. Fund the learning, not the build. A pilot you shut down on schedule for a small, bounded sum has not failed you. It did exactly what you paid it to do, which was to buy you out of a much larger mistake cheaply.
Then one day the pilot works, and a different trap opens, the more expensive one. It is tempting to treat a promising pilot as a proven business and jump straight to the full NPV. Still too early. It works, yes, but you do not yet know it works at scale, in production, against real volume and real people, at a cost per task that survives contact with the actual bill. The tool here is not a forecast at all. It is a set of bars you set in advance: a floor on how many people genuinely use it, a ceiling on what each task is allowed to cost, a specific movement in the one business metric that matters. Not predictions. Gates. You stop asking what will this return, and start asking what has to be true for this to be worth scaling, and has it come true yet. Then you hold the bars. Let what clears them through, and let what does not die quietly at validation cost instead of production cost.
And only at the far end, once the system really works and adoption is real and the unit economics are measured rather than hoped for, does the tool you reached for on day one finally become the right one. Now it is an ordinary investment. It has cash flows you can actually project, so run your normal NPV, your hurdle rate, your payback, and treat the close calls as close calls. There is nothing clever about the finance at this point, and that is exactly the point. The sophistication was never a fancier formula. It was the discipline not to demand the scaling formula from the two stages that could not possibly produce one.
Two faces of the same mistake
Hold the three together and the costly error comes into focus, and it wears two faces. Demand a scaling answer from an exploration bet and you kill good ideas for failing to produce a number that cannot exist yet, rejecting the future to protect a spreadsheet. Wave a half-formed idea straight through to full funding with no bars to clear and you pour real money into an untested shape. Same mistake, opposite directions, and both of them start the moment someone argues about the number before anyone has named the stage.
If this feels like it only applies to small internal pilots, look at who is admitting the very same thing at the top of the market. Ewout Steenbergen, the CFO of Booking Holdings, said in early October that "the hyperscalers that spend hundreds of billions on the development of their large language models, they don't really know what is going to be the ROI." Read that slowly. The people spending the most, under the most scrutinised budgets on earth, are telling you plainly that the early return number is not knowable yet. That is not a confession of weakness. It is an honest read of the stage they are in. The mistake would be to keep arguing over a figure everyone quietly knows is a placeholder, instead of asking the question that does have an answer: given the stage, what is the smallest amount we can spend to learn the most, and when exactly will we decide?
I am not a CFO, and I am not going to pretend any of this is easy to do in a live room with a hopeful team across the table. But the pattern seems hard to miss. The AI numbers that get fought over the longest are usually the ones nobody could ever have pinned down, because the stage was never named, so the number ends up standing in for a decision it was never able to make. You do not need to understand the model to ask what stage this is. You only need to be willing to say, out loud, we cannot price this yet, so here is what we will spend to find out.
My friend will get his house. He will also, I suspect, get a real number eventually, once there is a design for it to attach to. The number was never the problem. Pretending to have it before the thing existed was.
So, honestly: the last AI request you approved, what stage was it really in? And did the number everyone argued about match it? I would love to know.
Original source
Sources:
Ewout Steenbergen (EVP and CFO, Booking Holdings), quoted in Fortune, October 2, 2026: https://fortune.com/2026/10/02/booking-holdings-cfo-says-even-ai-hyperscalers-dont-know-their-roi-but-hes-learning-from-his-ai-coach
#CFO #FinOps #EnterpriseAI #AIROI #AIStrategy
Editorial note: The original article wording and sequence are preserved. The executive summary, section headings, takeaways and cover illustration are editorial additions.